Buying Jewelry or Expensive Gifts This Holiday Season? Your Insurance May Have Limits
The holiday season often brings more than decorations and family gatherings. It can also bring expensive purchases into the home: jewelry, watches, electronics, artwork, collectibles, and engagement rings.
If you’re planning to give—or receive—a valuable gift this season, there is one question worth asking:
Would your homeowners or renters insurance fully cover it if it were stolen, damaged, or lost?
The answer may surprise you.
Most homeowners and renters policies provide protection for personal belongings, but expensive items can be subject to special coverage limits. That means an item may technically be insured while still not being protected for its full value.
At The Beacon Insurance Agency, we believe the best time to discover those limits is before something happens—not when you’re filing a claim.
Your policy may cover jewelry—but not for its full value
The National Association of Insurance Commissioners (NAIC) specifically recommends reviewing your insurance before purchasing expensive jewelry or other valuable gifts.
Most homeowners and renters policies include jewelry as personal property, but the available coverage may not be enough for a high-value purchase. Policies can also treat different types of losses differently. For example, theft may be covered while accidental loss or damage may require additional protection (National Association of Insurance Commissioners, 2018).
Triple-I also explains that standard homeowners policies commonly place special limits of liability on jewelry, particularly for theft. If the value of your jewelry exceeds those limits, additional coverage may be necessary (Insurance Information Institute, n.d.).
Imagine receiving an expensive engagement ring for the holidays. The policy may provide some jewelry coverage, but that does not automatically mean the full value of the ring would be reimbursed after a covered loss.
That’s why checking the policy limits matters.
What does it mean to schedule a valuable item?
When standard coverage is not enough, there are ways to increase protection.
One option may be adding an endorsement or rider to the existing homeowners or renters policy. The NAIC explains that an endorsement changes the terms of an existing insurance contract and can add or increase coverage for items such as engagement rings, fine art, and collectibles (National Association of Insurance Commissioners, 2023).
Another approach is to schedule an individual valuable item, sometimes through a personal property floater.
Scheduled coverage can provide broader protection than the standard personal-property section of the policy. Depending on the insurer and contract, it may even cover certain accidental losses that would otherwise fall outside the standard policy.
For example, Triple-I notes that a floater can provide protection for situations such as accidentally losing a ring or leaving an expensive watch behind while traveling.
The right solution depends on the item, its value, the insurer, and the policy.
Documentation matters more than you might think
Insurance becomes much easier when you can show what you owned and what it was worth.
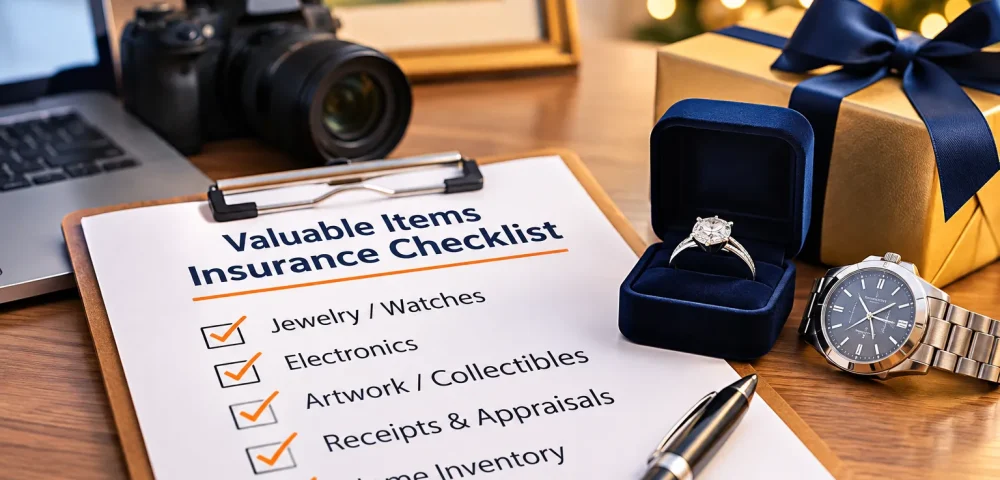
For valuable gifts, the NAIC recommends keeping photographs and adding expensive purchases to your home inventory. Jewelry, artwork, heirlooms and collectibles may also require professional appraisals, particularly when additional coverage is being requested.
A few simple habits can make a future claim much easier:
✓ Keep the receipt or purchase invoice.
✓ Photograph the item clearly.
✓ Obtain an appraisal when appropriate.
✓ Add the purchase to your home inventory.
✓ Keep copies of important documentation somewhere secure.
This becomes particularly important for items such as jewelry or collectibles whose value may change over time.
Don’t forget renters insurance
This issue isn’t limited to homeowners.
The NAIC specifically notes that both homeowners and renters policies may include jewelry as personal property while still limiting how much protection is available for expensive items.
Endorsements can also be added to renters policies when additional coverage is appropriate.
So if you rent an apartment and receive a valuable watch, engagement ring, piece of art or expensive collectible, your landlord’s insurance should not be assumed to protect it.
Your own policy is what matters.
When should you review your coverage?
You don’t need to call your insurance agent every time you buy a new phone or holiday gift.
But a significant purchase is a good reason to ask whether the value of what you own has changed enough to affect your coverage.
A new engagement ring, luxury watch, expensive camera, artwork, collectible or other high-value purchase may justify reviewing your policy limits.
The key questions are simple:
What is the item worth?
How much would my current policy actually pay?
Would additional coverage make sense?
At The Beacon Insurance Agency, we can help homeowners and renters understand their existing personal-property limits and determine whether valuable items may need additional protection.
Because a meaningful gift deserves more than a beautiful box.
It deserves the right protection too.
References
National Association of Insurance Commissioners. (2018, December 1). Learn How to Insure Expensive Jewelry & Gifts. https://content.naic.org/article/consumer-insight-learn-how-insure-expensive-jewelry-gifts
National Association of Insurance Commissioners. (2023, March 6). What You Need to Know About Adding an Endorsement or Rider to an Existing Insurance Policy. https://content.naic.org/article/what-you-need-know-about-adding-endorsement-or-rider-existing-insurance-policy
Insurance Information Institute (Triple-I). (n.d.). Do I Need Special Coverage for Jewelry and Other Valuables? https://www.iii.org/article/do-i-need-special-coverage-for-jewelry-and-other-valuables